 newsletter.semianalysis.comarticle
Datacenters 2027: The Year of Acceleration, +50GW in a Single Year
SemiAnalysis argues that global AI datacenter capacity will grow by about 50GW in 2027, against Brad Gerstner's guess of roughly 25GW. Evidence cited: over 24GW in advanced construction across 40 campuses, nearly USD 1T of binding leases signed in 2026, and record self-build starts. It also covers modular "LEGO" designs, behind-the-meter power and ex-US growth. The page text cuts off before the oversupply section.
What it claims
SemiAnalysis forecasts that global AI datacenter capacity will grow by about +50GW in 2027. The firm says this roughly equals all datacenter capacity built worldwide through 2024. The piece answers Brad Gerstner of Altimeter, who said on the All-In Podcast that SemiAnalysis's "+43GW in 2027" was too aggressive and guessed about 25GW. SemiAnalysis also expects its forecast to imply cheaper AI, faster model progress and revenue growth for leading labs. It also predicts very large capex and says interest rates will have to rise to fund the buildout.
How it works
The forecast rests on two leading indicators from SemiAnalysis's paid Datacenter Industry Model.
- Self-build construction starts: megawatts that begin construction each quarter, tracked per building for US hyperscalers. SemiAnalysis says this figure is "going parabolic," driven mainly by two hyperscalers it does not name in the free text.
- Leasing: developers typically spend only 5-10% of project capital before they sign a customer. A pre-lease is usually a 15-20 year contract worth $30-50B in total contract value per GW. Leases lead debt raises, and debt raises lead construction.
The page uses this chain to explain why 2026 growth was modest. Leasing was flat from H2 2023 to H1 2025, partly because of a Microsoft leasing freeze that SemiAnalysis says it flagged in December 2024. Oracle then signed about 4.5GW of IT capacity across three sites between August and October 2025. Meta, AWS, Microsoft, Google, Nvidia, AMD, Anthropic and OpenAI have since sought GW-scale leases, and neoclouds have signed 100MW-scale deals.
Evidence
- More than 24GW is in advanced construction across 40 campuses, most of it due in 2027. Many sites have exterior cooling and electrical gear installed.
- About $1T of binding lease value was signed in 2026 year-to-date. SemiAnalysis says its Compute, Capital & Markets Model confirms most of the matching debt has been raised.
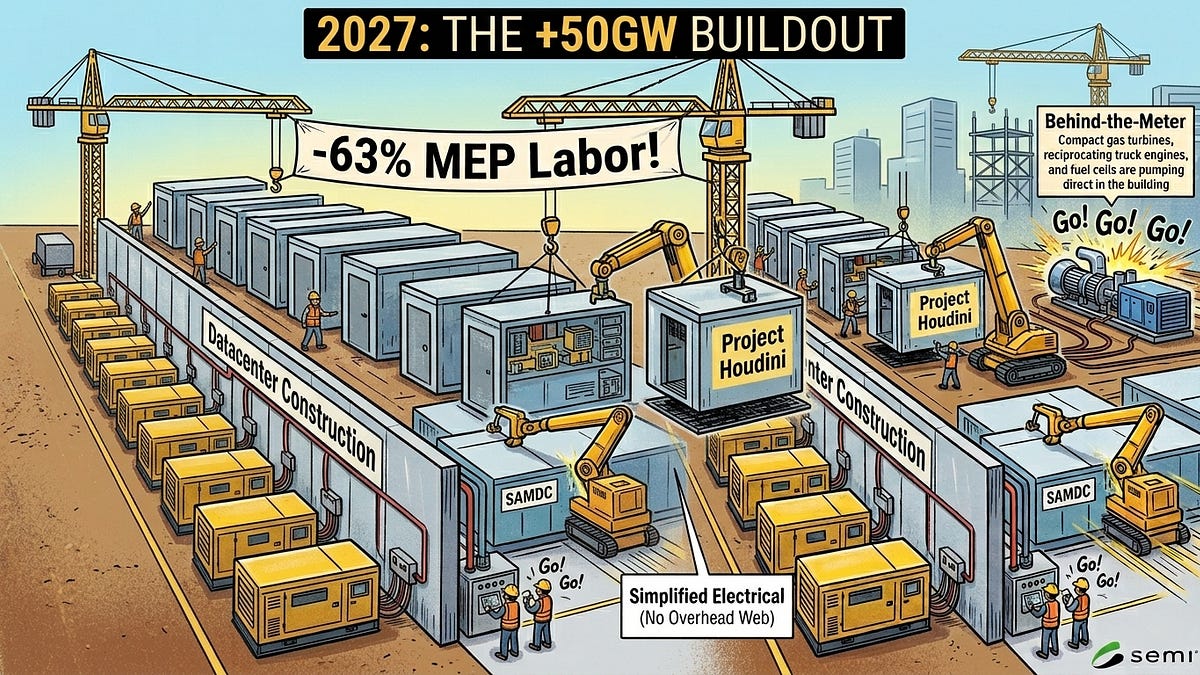
- Modular builds: Google uses prefabricated electrical modules in place of on-site outdoor cabling. Meta uses a tent design. AWS has a simplified shell called "SAMDC" and prefabricated data halls (Project Houdini). Construction now takes under 10 months, and MEP labor (normally 7-11 months) can fall by up to 63%.
- DayOne, a Singapore developer, has leased about 3GW since early 2023. It builds in about 9 months against more than 18 months for traditional developers, and it has signed deals with Firmus, OpenAI and Nvidia.
- Power: SemiAnalysis projects that US grid headroom turns negative at the end of 2027. Behind-the-meter generation avoids 5-10 year interconnection queues. New OEMs offering fuel cells, truck engines and refurbished turbines have eased turbine shortages at incumbents such as GE Vernova.
- Ex-US capacity accelerates sharply in 2027, and SemiAnalysis expects it to gain share in 2028.
Limits
The underlying data, including the two hyperscalers behind the rise in construction starts, sits behind paid SemiAnalysis models. Charts referenced in the text are not part of the fetched page. The piece gives two figures for its own forecast: Gerstner quotes +43GW, and the title says +50GW. The text says the lease total is "slightly under" $1T in one place and "over a trillion" in another. SemiAnalysis acknowledges labor shortages, vendor delays and funding problems, and cites Oracle's force-majeure delay at its New Mexico site in April. The claims that power is "largely solved" are the firm's own assessment. The oversupply section, which names memory and logic as possible top constraints in 2027-28, is cut off.
Organisations named here
- SemiAnalysis
- Altimeter
- Crusoe
- Amazon Web Services
- Microsoft
- Oracle
- Meta
- NVIDIA
- AMD
- Anthropic
- OpenAI
- Vertiv
- ABB
- All-In Podcast
- AWS
- Brad Gerstner
- DayOne
- Firmus
- GE Vernova (GEV)
- QTS
- Sterling Infrastructure
Technologies named here
- GPT-6
- Fable 5.5
- GEV
- Behind-the-meter generation
- Compute, Capital & Markets Model
- Datacenter Industry Model
- Fuel cells
- Gas turbines
- HPC Lease Tracker
- Industrials Model
- Modular datacenters
- Prefabricated electrical modules
- Project Houdini
- SAMDC
Techniques named here
- Behind-the-meter generation
- Modular (prefabricated) datacenter construction
- Pre-lease financing
Related in ai-infra
 github.comrepo
kerpopule/hermes-jev-skills

 huggingface.coarticle
Wire It, Run It, Deploy It: AI Workflows in Gradio


